MoBill Budget and Reminder

Screenshots
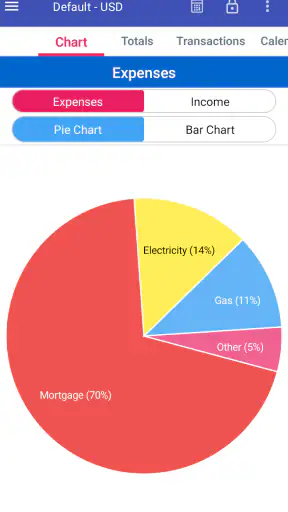
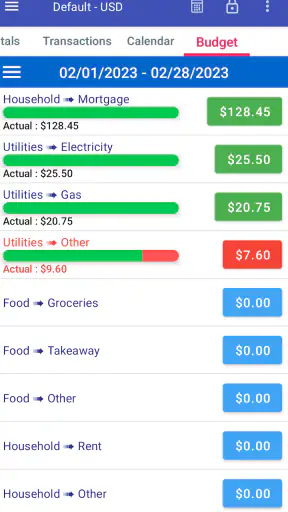
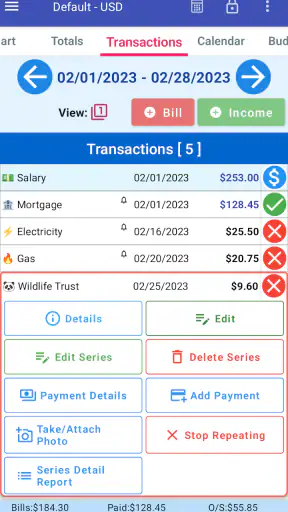
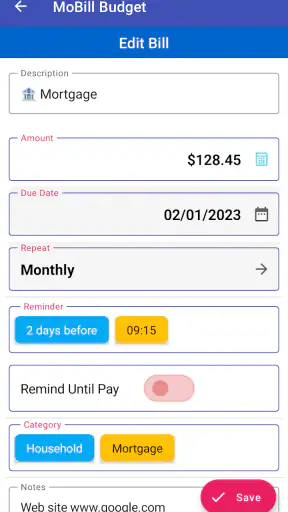
Details
- Rating
- 1.56K reviews
- Version
- 5.3.1
- Developer
- MoBill Apps
Analysis by Norviv
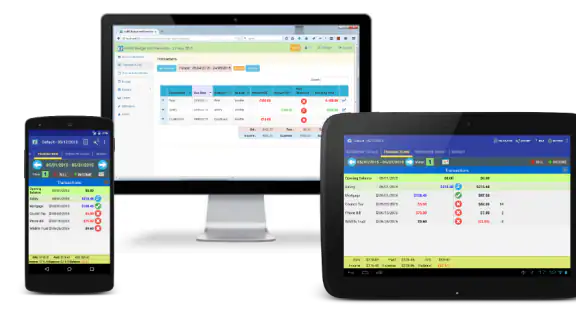
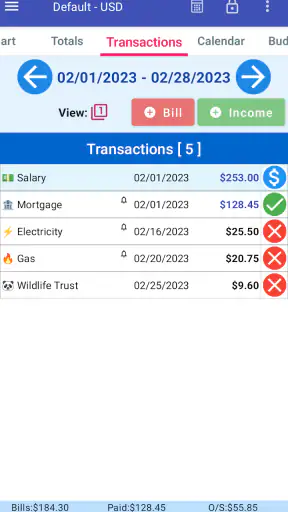
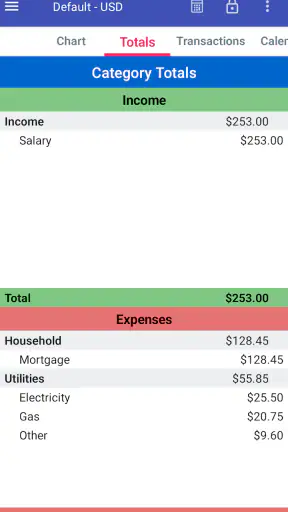
I usually judge a finance app by a simple question: will I still use it after the first week? MoBill Budget and Reminder makes a good case for staying because it focuses on the everyday work of personal finance rather than trying to become an all-in-one banking service. Its purpose is practical: help me keep track of spending, plan a budget, and remember upcoming bills in one place.
That focus matters. Many people do not need investment charts, bank transfers, or a complicated financial dashboard. They need to know what is due, what has already been spent, and whether the rest of the month is still manageable. MoBill Budget and Reminder, from MoBill Apps, is built around that kind of routine. I see it as a lightweight budgeting and bill reminder app for someone who wants more structure than a notes app but less complexity than a full financial management platform.
What I would consider before choosing it
My first decision criterion is the way I want to enter financial information. An app like this is most useful when I am comfortable recording transactions and obligations myself. That approach can feel reassuring because I decide what goes into the budget, but it also means the quality of the results depends on my consistency. If I forget to record a purchase, the picture becomes less reliable.
The second criterion is whether I need a private, manual overview or an automated connection to my financial life. MoBill Budget and Reminder is better suited to the first group. I would choose it when I want a clear personal routine for bills and spending, not when I expect every bank transaction to appear automatically or want a sophisticated financial analysis system.
The third question is how much detail I can realistically maintain. A budget that takes too long to update is likely to be abandoned. The appeal here is the possibility of keeping finances organized without turning every purchase into a major administrative task. At the same time, anyone who wants highly granular reports should think carefully about whether a simpler finance app will provide enough depth.
The app is free to install, with optional in-app purchases ranging from $2.50 to $10.99 per item. That makes it easy to try before deciding whether the extra paid options are worthwhile. I would not pay immediately. I would first create a normal month of bills and spending, then decide whether the basic workflow already solves my problem or whether the additional purchase would remove a real limitation.
A practical first setup
My preferred way to begin is not to enter every historical purchase. I would start with recurring obligations and the budget categories that affect daily decisions. Rent or housing, utilities, subscriptions, transport, groceries, and debt payments are more useful at the beginning than a long archive of old transactions.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Once those basics are in place, I would add the current balance or available amount that I am actually working with. The goal is to create a forward-looking picture. A finance app becomes much more helpful when it answers, “What can I safely spend before the next income arrives?” rather than merely showing what happened last month.
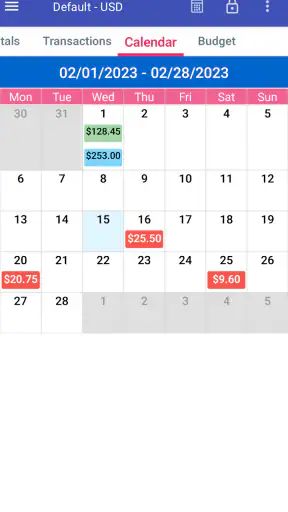
There is also a useful habit hidden in the reminder side of the product: I can treat bill dates as planning checkpoints instead of waiting for a late-payment scare. I would review the upcoming obligations at the start of each week, then adjust discretionary spending if several large payments are close together. That workflow is more valuable than opening the app only after money has already disappeared.
Where the app wins for everyday money control
The strongest part of this app is the combination of budgeting and reminders. A spending tracker on its own tells me where money went. A reminder tool on its own tells me when something is due. Bringing those jobs together makes the monthly picture easier to understand: an upcoming bill is not just a date on a calendar; it is an amount that competes with groceries, travel, and other plans.
I also like the fact that the concept is approachable. The store places it in the finance category, but it does not require me to think like an accountant. I can use it as a personal checklist with numbers attached. That makes it a reasonable starting point for someone who has tried spreadsheets and found them too rigid, or who has been relying on memory and repeatedly missed payment dates.
A realistic example would be a household paid near the end of the month. During the first week, there is a temptation to spend freely because the account looks healthy. I would use the app to record the fixed bills that are still ahead, then look at the remaining amount before making larger purchases. The benefit is not a magical saving feature; it is the pause created by seeing commitments before treating the balance as disposable.
Another useful scenario is irregular income. A freelancer or shift worker may not receive the same amount on every payday. In that case, a rigid monthly target can be misleading. I would use the app more conservatively: enter known obligations first, keep a buffer for uncertain income, and use reminders to prevent fixed payments from being forgotten. It may not replace a detailed cash-flow spreadsheet, but it can provide a simpler layer of control.
Three habits that make it more useful
First, I would separate essential commitments from flexible spending as early as possible. This is not just a matter of neat labels. It changes the decision I make when the month becomes tight. If the app shows that the remaining money is mostly reserved for bills, I know that reducing entertainment or restaurant spending is more realistic than pretending the whole balance is available.
Second, I would record a purchase soon after making it instead of saving everything for one end-of-week session. Delayed entry creates two problems: forgotten small purchases and a false sense of available money. A quick entry routine, even if it is not perfect, is usually more useful than an ambitious system that I update only occasionally.
Third, I would use reminders as review points, not merely alarms. Before a large payment is due, I would check whether the budget still reflects reality. If a bill changed or an unexpected expense appeared, that is the moment to adjust the plan. This turns reminders into a small financial maintenance routine rather than a series of isolated notifications.
These habits reveal an important trade-off. Manual control gives me a chance to think about each expense, but it also asks for attention. The app can organize my decisions; it cannot make those decisions for me. That is a strength for people who want awareness and a weakness for people who want complete automation.
Who will probably appreciate the design
I would recommend trying it to a student managing bills for the first time, a couple looking for a shared household overview, or anyone who wants a straightforward way to remember recurring payments. It can also suit a person who wants to move away from paper notes without committing to a large financial platform.
The age rating is Everyone, which fits the general purpose of the app. Its value is not limited to one age group, although the best results will come from users willing to build a regular money-checking habit. Someone who enjoys manual planning may find that process calming and clear.
The app also has a long history, having been released on February 28, 2011. That does not automatically make it better than newer competitors, but it does suggest that the basic idea has remained useful over time. The current version is 5.3.1, and it requires Android 8.0 or later. For someone using an older device, compatibility should be checked before planning a move from another finance tool.
Its reach is substantial, with over 500 thousand installs, while the average rating sits at 4.0 from around 3.8 thousand ratings. I read those figures as a sign of a useful but not universally perfect tool: enough adoption to show that the concept works for many people, but not a reason to ignore personal preferences about automation, reporting, or interface style.
Where another type of app may fit better
I would look elsewhere if automatic bank synchronization is essential. A bank-connected budgeting service can reduce manual entry and may be more convenient for someone with many accounts or frequent card transactions. The trade-off is that those services can feel less private or less predictable, depending on how connections and account access are handled. MoBill’s manual approach is better when I want to choose exactly what I record.
A spreadsheet may be a better alternative for someone who needs custom formulas, detailed forecasting, or a budget shared across unusual categories. Spreadsheets require more setup and maintenance, but they offer flexibility that a focused mobile app may not match. I would choose the spreadsheet route for a complex household or business-like budget, not for a quick daily spending routine.
A calendar or task app can handle simple bill reminders, but it usually does not provide the same budgeting context. I might remember that a payment is due without understanding how it affects the rest of the month. MoBill is more appropriate when the date and the amount need to be considered together.
On the other hand, people who want investments, net-worth tracking, shared financial goals, receipt scanning, or elaborate visual reports may find this app too narrow. I would not select it as the only tool for a complicated financial portfolio. Its strength is keeping ordinary personal obligations visible, not covering every possible money-management task.
The cost of changing from another system
Switching is easiest when I start with the current month rather than trying to recreate years of financial history. I would transfer active bills, current budget limits, and the balance that matters today. Old records can remain in the previous app or spreadsheet unless I genuinely need them for comparison.
The main cost is not money; it is rebuilding the habit. Any manual finance tool asks me to decide on categories, enter transactions, and review the result. I would make the transition during a quiet part of the month, then keep the previous method available briefly as a reference. That reduces the risk of missing a bill while I learn the new routine.
The free entry point lowers the financial risk of testing it. Still, optional purchases mean I would pay attention to what I actually need rather than assuming every extra option is necessary. If the basic workflow handles my bills and spending, there may be no reason to spend more. If a paid item makes the app significantly easier to maintain, I would judge it against the time saved, not against the price alone.
One limitation I would take seriously is the possibility of manual fatigue. During a busy week, skipping several entries can make the budget look healthier than it is. My workaround would be a short weekly review and a conservative buffer. If I know I will not maintain that routine, an automated alternative may be more suitable even if it gives me less direct control.
My recommendation for different kinds of users
I would recommend MoBill Budget and Reminder to someone who wants a focused, hands-on way to organize personal finances and upcoming bills. It is especially appealing if the real problem is forgetting obligations or spending without accounting for what is still due. The free price makes the trial decision straightforward, and the Everyone rating keeps the app approachable for a broad audience.
I would skip it as a primary finance tool if I expect automatic account imports, advanced investment management, or a highly customized financial model. In those cases, a connected finance service or spreadsheet is likely to fit better. I would also avoid relying on it without a recording routine; no reminder can repair a budget built from incomplete spending information.
For me, the clearest reason to choose it is balance. It is more purposeful than a basic notes list, but less demanding than a full financial command center. I can use it to see what needs attention, decide what is safe to spend, and establish a repeatable monthly check-in. The best results come from treating it as a daily money habit, not as a passive record of the past.
MoBill Apps has kept the product centered on a familiar need: keeping personal finance and a budget under control. That simplicity will not satisfy everyone, but it is exactly why I can recommend it to users who want practical organization without unnecessary financial machinery. If your priority is visibility, reminders, and manageable manual planning, this is a sensible app to try. If your priority is automation or deep analysis, I would spend the time comparing other categories before switching.
Frequently Asked Questions
01What is MoBill Budget and Reminder used for?
MoBill Budget and Reminder is designed to help you organize personal finances by tracking bills, expenses, income, and recurring payments in one place. You can use it to record upcoming obligations, monitor due dates, and maintain a clearer view of your monthly budget. It is especially useful if you often forget payment deadlines or want a simple way to review regular household spending.
02Can MoBill Budget and Reminder send reminders for upcoming bills?
Yes, reminders are one of the app’s main purposes. You can enter a bill, assign its amount and due date, and configure a notification so you are alerted before payment is required. This can be helpful for rent, subscriptions, utilities, loans, and other recurring expenses. Notification behavior may depend on your device permissions, battery settings, and the reminder options available in your installed version.
03Does MoBill Budget and Reminder require an internet connection?
The app is primarily intended for entering and reviewing financial information on your device, so many basic functions may work without a continuous internet connection. However, features such as synchronization, backups, updates, or integrations—if included in your version—could require connectivity. Before relying on the app for important reminders, make sure notifications are enabled and test how it behaves when your phone is offline.
04Is MoBill Budget and Reminder safe for storing financial information?
MoBill Budget and Reminder can be convenient for recording bills and budget details, but users should still treat all financial data carefully. Avoid entering highly sensitive information such as online banking passwords, full card security codes, or account credentials. Review the app’s privacy policy, requested permissions, backup options, and data-storage practices before adding personal information, and protect your device with a secure passcode or biometric lock.
05Is MoBill Budget and Reminder free to download and suitable for beginners?
The app is generally aimed at users who want a straightforward budgeting and bill-reminder tool rather than a complex accounting system. Its basic workflow—adding expenses, setting due dates, and checking payment schedules—should be approachable for beginners. Availability of free features, advertisements, premium tools, or in-app purchases can vary by platform and version, so check the Google Play Store or Apple App Store listing before downloading.


